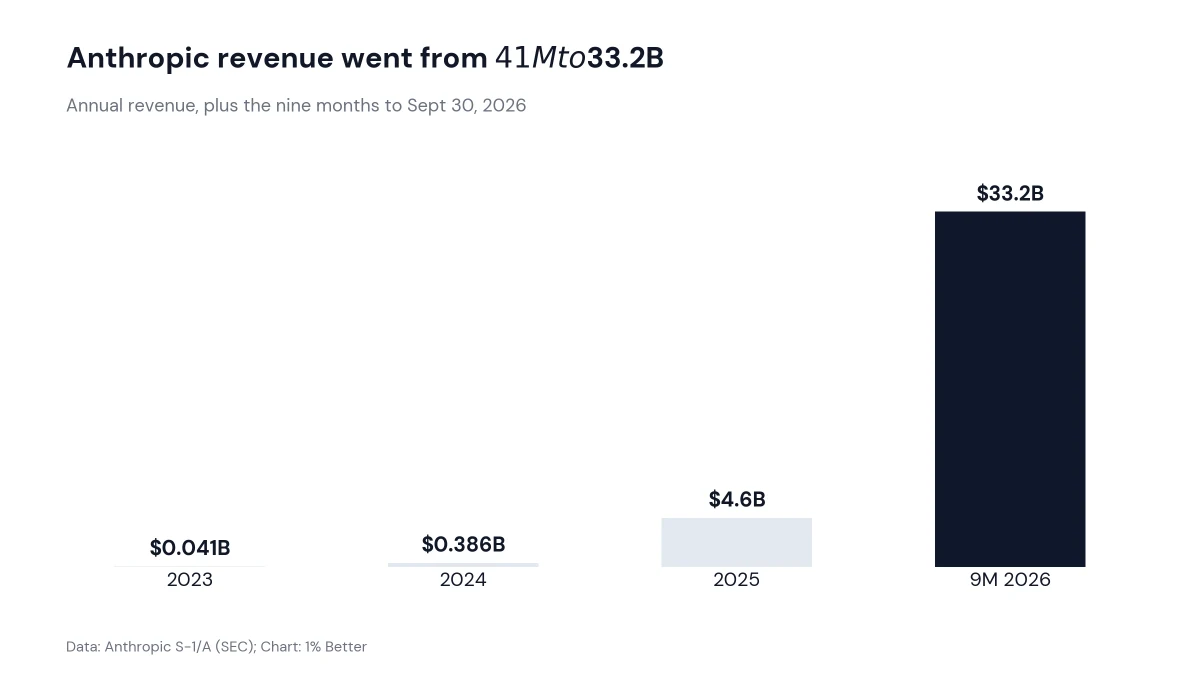
Anthropic's amended IPO prospectus, filed Monday, shows revenue of $33.2 billion for the nine months to September 30, up 1,206% from a year earlier.
By the numbers: Revenue ran $41 million in 2023, $386 million in 2024 and $4.6 billion in 2025. The three months to September 30, 2026 alone brought in $17.0 billion.
Zoom in: The operating loss narrowed to $1.3 billion for the nine months to September 30, 2026 from $5.2 billion a year earlier, which the filing credits to revenue growth plus compute and operating efficiency.
- Headcount went from about 940 at the end of 2024 to about 5,300 on September 30, 2026. Trailing twelve month revenue per employee rose from $1.4 million to over $6.6 million.
The big picture: Consumption-based revenue reached $26.3 billion, or 79% of the total, over the nine months, while subscriptions contributed $6.9 billion, or 21%. A growing share of enterprise customers sign multi-year contracts with minimum spend commitments.
What's next: Anthropic applied to list Class A shares on the Nasdaq Global Select Market under the symbol ANT. Monday's amendment adds public offerings in Australia, Canada, parts of the European Economic Area, Japan, Switzerland and the United Kingdom.
Yes, but: The price range and the share count are still blank in the filing, and the company warns its recent growth may reflect early-stage adoption dynamics that may prove unsustainable over time.
Between the lines: Anthropic is a Delaware public benefit corporation and a controlled company: the Long-Term Benefit Trust holds the Class T stock and can generally elect a majority of the board.
Why it matters: This is the clearest public read yet on what frontier AI demand is worth. A company that booked $41 million of revenue in 2023 booked $17.0 billion in a single quarter this year, and it is close to a ticker symbol.