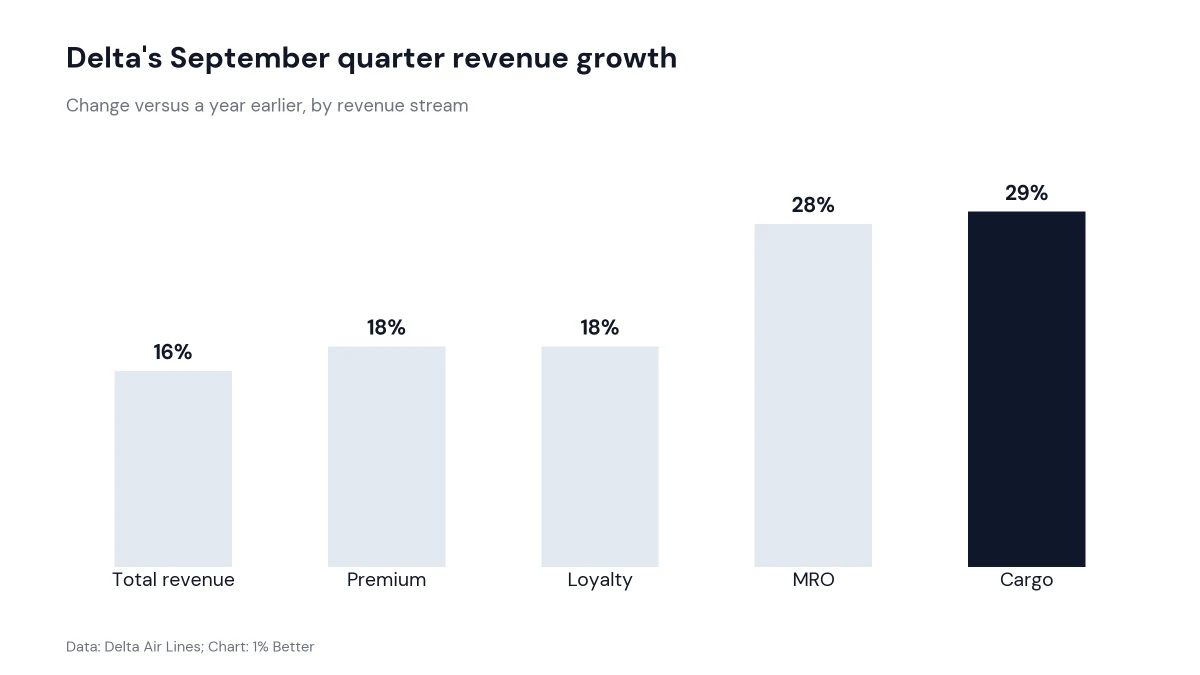
Delta reported record September quarter revenue of $17.6 billion on Friday and said it expects a full-year pre-tax profit of roughly $4.5 billion while absorbing a $6 billion increase in fuel costs.
By the numbers: September quarter revenue grew about 16% over last year on flat capacity, and adjusted earnings came in at $1.72 a share. Pre-tax profit was $1.5 billion, matching last year.
- Full-year guidance is $5.10 to $5.60 a share, with free cash flow of roughly $2.5 billion and an operating margin of 7% to 9%.
The big picture: CEO Ed Bastian said air travel continues to be one of the best values in the consumer economy and that demand remains strong, supported by consumers’ growing preference for experiences and travel.
- CFO Erik Snell said the quarter absorbed more than $500 million of higher fuel costs compared with guidance in early July.
Zoom in: Premium revenue grew 18% and cargo revenue 29%. American Express remuneration grew 15% in the quarter and is on pace to exceed $9 billion for the full year.
- Domestic unit revenue grew 16% and Latin America led international performance at 22%.
Yes, but: Non-fuel unit costs rose 7.3% over the prior year on flat capacity, driven by higher crew and revenue-related costs, including nearly a point of impact from summer storms.
Between the lines: Corporate sales grew double digits in every sector, led by banking, technology and energy, and over 90% of surveyed corporate customers expect their 2027 travel to increase or stay the same.
What's next: Delta guides to December quarter revenue growth of about 20% and earnings of $1.15 to $1.65 a share, assuming an all-in fuel price near $4.25 a gallon.
Why it matters: Airlines recover fuel costs through fares, and Delta’s unit revenue climbed 15% while seats stayed flat, which is what a fuel shock looks like on a ticket price.